How much diesel will the Trump-Putin agreement release?
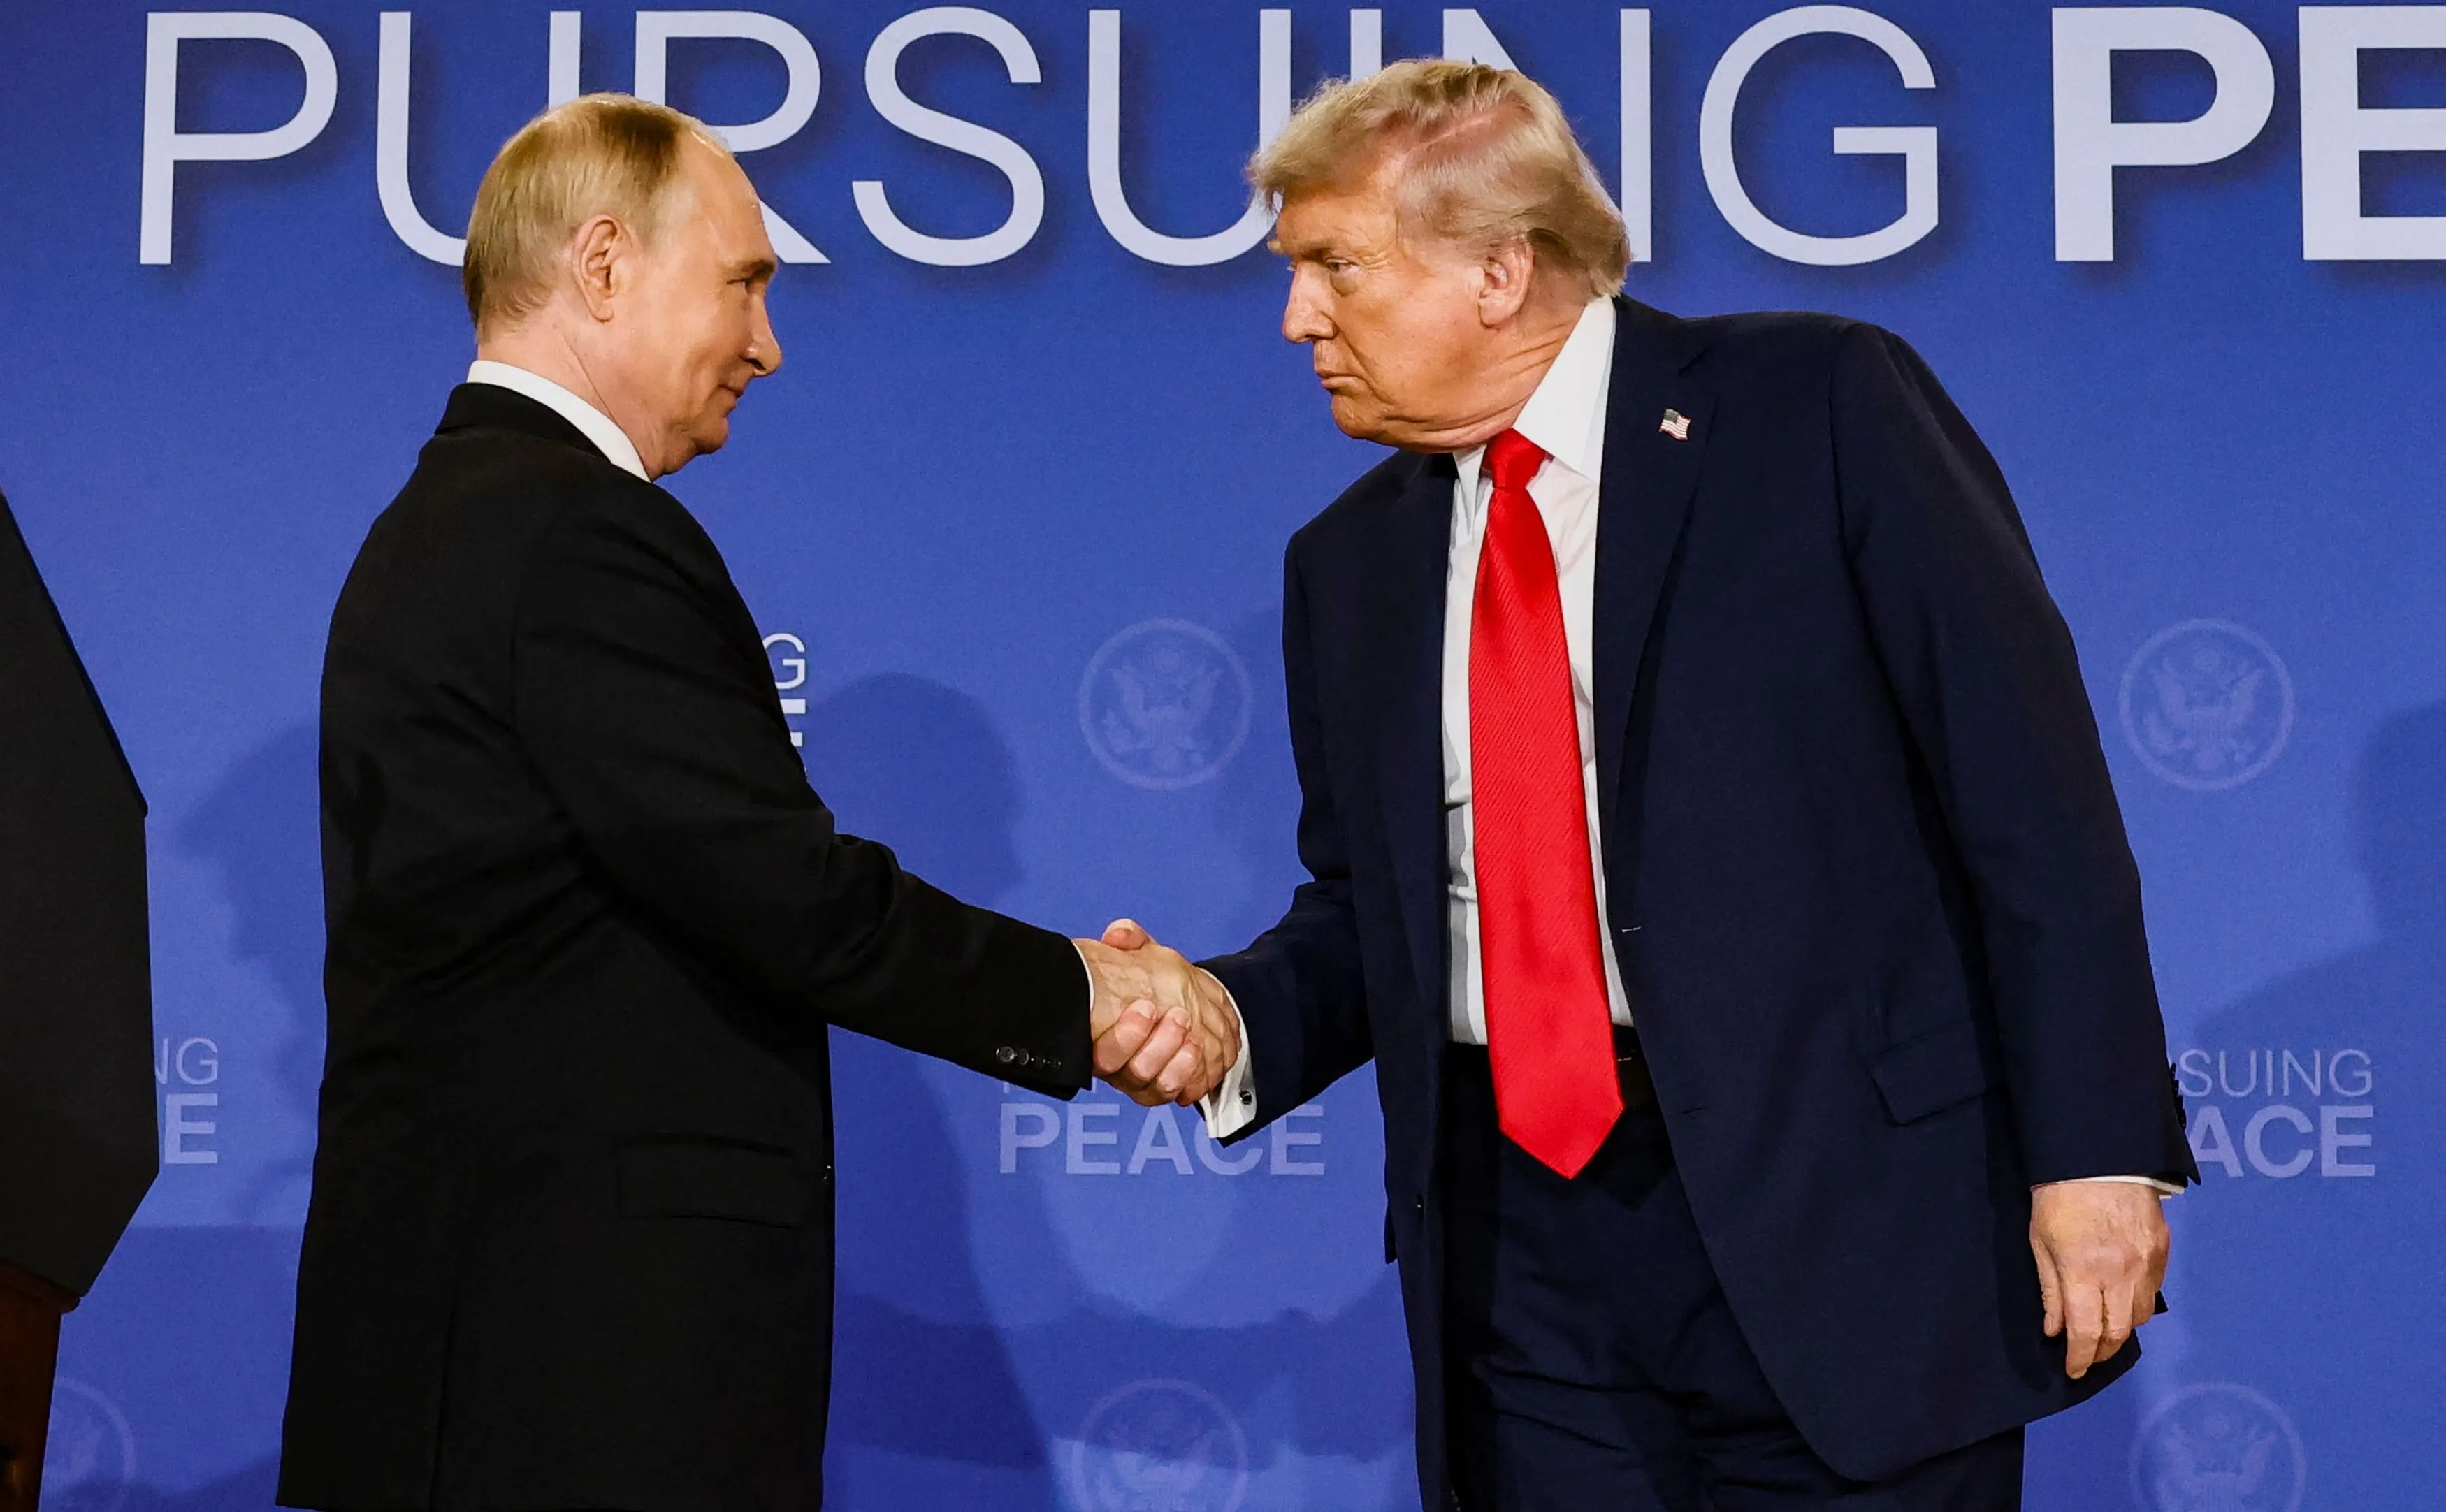
The agreement, reached following communications between US President Donald Trump and Russian President Vladimir Putin, outlines a phased release of Russian diesel into international markets. According to the announcement on October 9, 2026, the initial phase involves more than 300,000 tonnes of diesel. This is followed by an additional 500,000 tonnes scheduled for November and a subsequent 1 million tonnes. Furthermore, President Trump indicated that an extra 3 million tonnes could be made available, contingent upon the operational status of Russian refineries.
If all announced quantities are realized without overlap, the total volume of diesel moving through the market could reach 4.8 million tonnes. This represents a substantial increase in supply that will test the capacity of the global product tanker fleet. The scale of this movement is particularly noteworthy given the current volatility in maritime trade routes, including tensions in the Middle East and navigation challenges in the Strait of Hormuz, both of which have previously driven up freight rates and constrained vessel availability.
Which vessel types will drive this shipping demand?
The logistics of transporting 4.8 million tonnes of diesel will rely on three primary categories of product tankers: MR, LR1, and LR2. The specific mix of vessels used will depend on port constraints, destination requirements, and the technical specifications of the available fleet. The sheer volume of the cargo necessitates a strategic approach to vessel deployment to ensure efficient delivery across diverse global markets.
Comparing MR, LR1, and LR2 tanker capacities
The different vessel classes offer varying levels of capacity and range, which dictates how they will be deployed for these new diesel cargoes:
- MR (Medium Range): These vessels typically have a deadweight tonnage (dwt) between 25,000 and 55,000. At their upper limit, they can carry approximately 45,000 to 50,000 tonnes of diesel per voyage, making them ideal for regional trade and smaller port access.
- LR1 (Long Range 1): Designed for longer distances, these vessels can carry an indicative load of approximately 60,000 to 65,000 tonnes of diesel per trip, serving larger international trade routes.
- LR2 (Long Range 2): The largest category, with capacities ranging from 80,000 to 120,000 dwt, these are most suited for massive long-distance movements, such as transatlantic voyages, due to their economies of scale.
A potential scenario for transporting the full 4.8 million tonnes involves a combination of 30 MR voyages, 20 LR1 voyages, and 25 LR2 voyages, totaling 75 trips. If the market relied solely on MR tankers, it would require up to 96 voyages, whereas LR2 tankers could complete the task in as few as 60 voyages. Even if we only consider the initial 1.8 million tonnes, the workload remains significant, requiring 36 MR, 28 LR1, or 23 LR2 voyages. It is important to note that these numbers do not imply a need for new ship construction; as deliveries are phased, the same vessels can execute multiple voyages.
What is the impact on tonnages and freight rates?
The sudden influx of diesel is expected to influence global tonnages, particularly for the LR2 segment. Because these larger vessels are often used for long-haul routes, they are highly sensitive to changes in supply-and-demand dynamics for long-distance transport.
If a significant portion of the Russian diesel is destined for the United States or other distant markets, the demand for LR2 tonnages will likely rise. Increased demand for these specific long-range trips can lead to vessels being tied up for longer durations, which effectively reduces the available supply in the spot market. This reduction in available tonnage is a primary driver for higher freight rates. While MR tankers provide more flexibility for smaller loads and diverse ports, the LR2 vessels provide the heavy lifting required for global redistribution, potentially tightening the market for long-haul product tankers. The ultimate impact, however, remains unsettled, as it depends on whether these quantities represent entirely new exports or simply a reallocation of existing trade flows.
How do sanctions and the new US license affect shipping?
The regulatory environment has shifted following the US Treasury Department's decision on October 9, 2026, to issue General License 135 through the Office of Foreign Assets Control (OFAC). This license provides a temporary exemption for transactions involving the sale, delivery, unloading, and importation of Russian diesel, with validity lasting until April 7, 2027.
Crucially, this license is not limited to cargoes that were already loaded before the announcement; it creates a legal window for new loadings to occur, provided they meet the specific terms of the US exemption. However, this does not constitute a general lifting of sanctions against Russia. European Union and United Kingdom sanction regimes remain in place, creating a complex compliance landscape for shipowners operating in those jurisdictions. The central question for the industry is whether the US exemption will be sufficient to encourage charterers, insurers, and banks to engage with these cargoes, or if existing restrictions will continue to push much of this trade into the "shadow fleet" to avoid Western financial and regulatory oversight.
Frequently asked questions
How many tanker voyages are expected from this deal?
The total number of voyages is estimated to be between 60 and 100, depending on the vessel sizes used. A mix of MR, LR1, and LR2 tankers will likely be employed to move the projected 4.8 million tonnes of diesel across global markets.
What is the role of General License 135?
General License 135, issued by OFAC, provides a temporary legal exemption for transactions related to Russian diesel until April 7, 2027. It allows for the sale, delivery, and importation of these specific cargoes, potentially opening a window for new shipments to be legally processed under US law.
Will this deal lead to new ships being built?
No, the market is not expected to seek an equal number of new vessels. Because the diesel deliveries will be phased in over time, the same vessels can perform multiple voyages, meaning the existing fleet will likely absorb the increased workload through repeated trips.
Why are LR2 tankers particularly important?
LR2 tankers are vital because they offer economies of scale for long-distance transport. If the diesel is sent to distant markets like the US, these vessels will see increased demand, which can tie up supply and support higher freight rates.
Does this agreement lift all Russian sanctions?
No, the agreement and the US General License are specific to diesel transactions. Other sanctions imposed by the US, the EU, and the UK remain in effect, meaning shipowners must still navigate a complex web of international regulations.
Key takeaways
- The Trump-Putin deal could mobilize up to 4.8 million tonnes of Russian diesel.
- Shipping requirements are estimated at 60 to 100 total tanker voyages.
- OFAC General License 135 provides a legal window for diesel trades until April 2027.
- LR2 tankers are expected to see increased demand for long-distance routes.
- EU and UK sanctions remain active despite the US regulatory exemption.
Conclusion
The agreement between the US and Russia introduces a significant variable into the global product tanker market. By potentially releasing millions of tonnes of diesel, the deal creates a substantial logistical undertaking that will require a strategic mix of MR, LR1, and LR2 vessels. While the US General License 135 provides a necessary regulatory pathway for new loadings, the persistence of EU and UK sanctions ensures that the maritime industry must proceed with caution. The ultimate impact on freight rates and market stability will depend on whether these volumes are absorbed by the conventional fleet or continue to rely on the shadow fleet.