Why is France facing a fiscal deadlock in 2026?
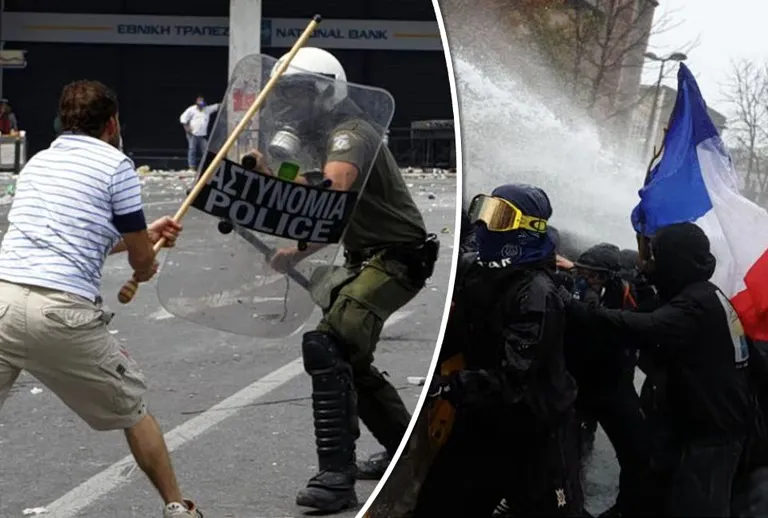
The French government is currently struggling to balance massive public spending against a rising cost of borrowing that threatens to trigger a sovereign debt crisis. Social unrest has intensified, with approximately 1.6 million people participating in nationwide protests in early November 2026. These demonstrations, involving teachers, healthcare workers, and railway employees, are driven by the high cost of living and significant cuts to public services.
The underlying cause of this instability is a deepening fiscal impasse within the second-largest economy of the eurozone. While President Emmanuel Macron has attempted to address the 'justified demands' at the heart of these social movements, the government's ability to provide relief is constrained by its massive debt obligations and the need to comply with European fiscal rules.
How does the French debt compare to the Greek crisis of 2011?
France's debt levels are significantly higher in absolute terms than those seen during the peak of the Greek debt crisis. According to economist Wolfgang Münchau, while Greece owed approximately €350 billion in 2011, France's debt has reached roughly €3.6 trillion. This ten-fold difference in scale changes the nature of the potential fallout for the European Union.
The mechanics of the risk are similar, yet the implications are broader. In 2010, the Greek crisis exposed fundamental weaknesses in the eurozone's architecture, leading to bailouts from the IMF and European partners in exchange for austerity measures. However, Münchau suggests that because France is a cornerstone of the eurozone, a failure to manage its debt would require resources far exceeding those used to rescue Greece.
The vicious cycle of rising interest rates
A critical indicator of the current risk is the cost of borrowing. As of November 2026, the yield on French ten-year bonds has exceeded 5%, a level that is approaching crisis territory. This creates a dangerous feedback loop:
- Higher interest rates increase the cost of servicing existing national debt.
- Increased debt servicing expands the annual fiscal deficit.
- A widening deficit necessitates more borrowing.
- Increased borrowing demand drives interest rates even higher.
Münchau warns that once investors lose confidence in a country's ability to repay, this cycle becomes nearly impossible to break without massive external intervention.
What role did Emmanuel Macron's policies play?
The current economic instability is being attributed by some analysts to the policy trajectory established during Emmanuel Macron's presidency. Wolfgang Münchau argues that the administration's early approach contributed to the present deadlock. Specifically, the implementation of austerity measures is believed to have fueled social violence, while cuts to public investment may have discouraged private sector engagement.
The political landscape in France is now characterized by an almost impossible balancing act for any future leadership. A successful candidate would need to achieve four conflicting goals simultaneously:
- Controlling the massive fiscal deficit.
- Preventing widespread social unrest and violence.
- Complying with strict European Union fiscal regulations.
- Maintaining France's position within the eurozone.
Münchau suggests that it is highly unlikely any leader can satisfy all these requirements, noting that "something will have to give" in one of these areas.
Is the eurozone structurally prepared for a French crisis?
The structural integrity of the eurozone remains a central concern, as the monetary union is viewed by some experts as an incomplete project. Wolfgang Münchau posits that the European Union made a fundamental error by creating a monetary union without completing the necessary fiscal and political integration. He describes the current state as an "incomplete monetary union" that is inherently unsustainable.
While the European Central Bank (ECB) managed to stave off an immediate collapse during previous crises through quantitative easing and bond-buying programs, these were temporary fixes. The underlying issue of economic divergence between eurozone member states remains unresolved. The tools used to manage smaller economies like Greece may prove insufficient for a systemic crisis involving a major power like France.
The risk of a default and Eurozone exit
Although no major political candidate in France currently advocates for leaving the eurozone, a default remains a theoretical possibility if the state cannot service its debt. A default would not automatically result in an exit from the euro, as complex legal and political processes would follow. However, Münchau notes that leaving the eurozone might eventually become the "easier option" for a future president if the consequences for the global economy are deemed secondary to national stability. This is because sovereign bonds serve as essential collateral for the liquidity that commercial banks receive from the ECB.
What is the current consensus on the economic outlook?
There is a growing sense that many policymakers are currently operating under an illusion of control. Münchau observes that while governments claim the situation is manageable through minor budgetary adjustments, the reality is that ministers of all political stripes are finding it increasingly difficult to implement the necessary changes. The window for preventative action appears to be closing as market perceptions shift.
The core of the problem lies in the fact that the solutions implemented over the last 15 years addressed the symptoms of the eurozone's instability rather than its structural causes. Without a more profound integration of fiscal policies, the eurozone remains vulnerable to the next major sovereign debt shock, which, if centered in France, could be transformative for the entire global financial system.
Frequently asked questions
How much debt does France currently hold?
France's debt is approximately €3.6 trillion. This figure is nearly ten times the amount Greece owed during its debt crisis in 2011, which was roughly €350 billion. This massive scale makes a French fiscal crisis significantly more complex to manage than previous eurozone crises.
Why are there protests in France in 2026?
Protests in France are driven by the rising cost of living and significant cuts to public services. Approximately 1.6 million people, including teachers and healthcare workers, have taken to the streets to express dissatisfaction with the government's handling of the economy and social welfare.
What is the risk of a 'vicious cycle' in French debt?
A vicious cycle occurs when rising interest rates increase the cost of debt servicing, which expands the fiscal deficit. This expansion requires more borrowing, which in turn drives interest rates even higher, making the debt even more expensive to manage and potentially leading to a default.
Can France stay in the eurozone if it defaults?
A default does not automatically trigger an exit from the eurozone due to the complex legal processes involved. However, a default could lead to a loss of confidence that makes remaining in the euro increasingly difficult, potentially making an exit a more pragmatic choice for future governments.
What does Wolfgang Münchau say about the Eurozone?
Wolfgang Münchau argues that the eurozone is an incomplete and unsustainable monetary union. He believes that because the union lacks full fiscal integration, it remains vulnerable to economic divergence between member states and cannot easily manage a crisis involving a major economy like France.
Key takeaways
- France's €3.6 trillion debt is roughly ten times larger than Greece's 2011 debt.
- French ten-year bond yields have exceeded 5%, signaling rising market risk.
- Massive social unrest involving 1.6 million people is impacting French stability.
- The eurozone faces structural risks due to being an incomplete monetary union.
Conclusion
The fiscal situation in France represents a systemic challenge that extends far beyond national borders. The sheer scale of France's €3.6 trillion debt, combined with rising interest rates and intense social volatility, creates a risk profile that exceeds the Greek crisis of 2011. As Wolfgang Münchau highlights, the eurozone's current structure—an incomplete monetary union—may lack the necessary tools to absorb a shock of this magnitude. Whether the French government can navigate this impasse without triggering a wider eurozone crisis remains the defining economic question of 2026.